Uploaded May 2018 | Updated September 2026, 2 hours ago
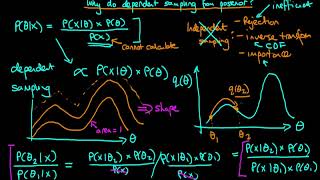
One solution to approximating high dimensional integrals involves discretising. These approaches involve approximating a continuous function as a discrete function, with a finite set of values at particular points. This video explains the issue inherent with this approach to doing approximate Bayesian inference.
This video is part of a lecture course which closely follows the material covered in the book, "A Student's Guide to Bayesian Statistics", published by Sage, which is available to order on Amazon here: amazon.co.uk/Students-Guide-Bayesian-Statistics/dp/1473916364
For more information on all things Bayesian, have a look at: ben-lambert.com/bayesian/. The playlist for the lecture course is here: youtube.com/playlist?list=PLwJRxp3blEvZ8AKMXOy0fc0cqT61GsKCG&disable_polymer=true
One solution to approximating high dimensional integrals involves discretising. These approaches involve approximating a continuous function as a discrete function, with a finite set of values at particular points. This video explains the issue inherent with this approach to doing approximate Bayesian inference.
This video is part of a lecture course which closely follows the material covered in the book, "A Student's Guide to Bayesian Statistics", published by Sage, which is available to order on Amazon here: amazon.co.uk/Students-Guide-Bayesian-Statistics/dp/1473916364
For more information on all things Bayesian, have a look at: ben-lambert.com/bayesian/. The playlist for the lecture course is here: youtube.com/playlist?list=PLwJRxp3blEvZ8AKMXOy0fc0cqT61GsKCG&disable_polymer=true