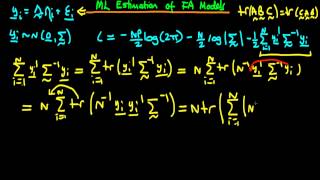Uploaded February 2014 | Updated September 2026, 2 hours ago
This video provides an example as to how we can use the model estimated variance-covariance matrices for the factors and errors in order to derive the variance and covariance of indicators. Check out ben-lambert.com/econometrics-course-problem-sets-and-data for course materials, and information regarding updates on each of the courses. Quite excitingly (for me at least), I am about to publish a whole series of new videos on Bayesian statistics on youtube. See here for information: ben-lambert.com/bayesian Accompanying this series, there will be a book: amazon.co.uk/gp/product/1473916364/ref=pe_3140701_247401851_em_1p_0_ti
This video provides an example as to how we can use the model estimated variance-covariance matrices for the factors and errors in order to derive the variance and covariance of indicators. Check out ben-lambert.com/econometrics-course-problem-sets-and-data for course materials, and information regarding updates on each of the courses. Quite excitingly (for me at least), I am about to publish a whole series of new videos on Bayesian statistics on youtube. See here for information: ben-lambert.com/bayesian Accompanying this series, there will be a book: amazon.co.uk/gp/product/1473916364/ref=pe_3140701_247401851_em_1p_0_ti