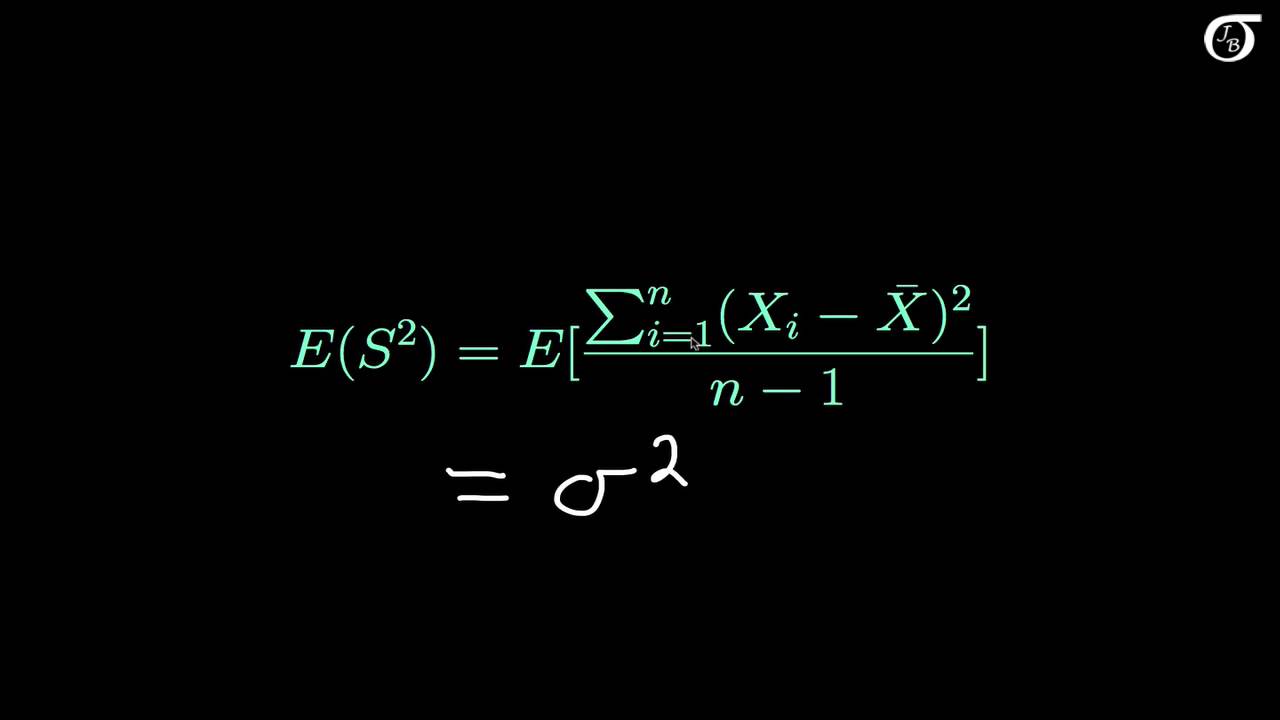
Uploaded January 2014 | Updated September 2026, 1 hour ago
A proof that the sample variance (with n-1 in the denominator) is an unbiased estimator of the population variance.
In this proof I use the fact that the sampling distribution of the sample mean has a mean of mu and a variance of sigma^2/n. If you need that to be shown as well, I show that in this video: youtu.be/7mYDHbrLEQo.
A proof that the sample variance (with n-1 in the denominator) is an unbiased estimator of the population variance.
In this proof I use the fact that the sampling distribution of the sample mean has a mean of mu and a variance of sigma^2/n. If you need that to be shown as well, I show that in this video: youtu.be/7mYDHbrLEQo.