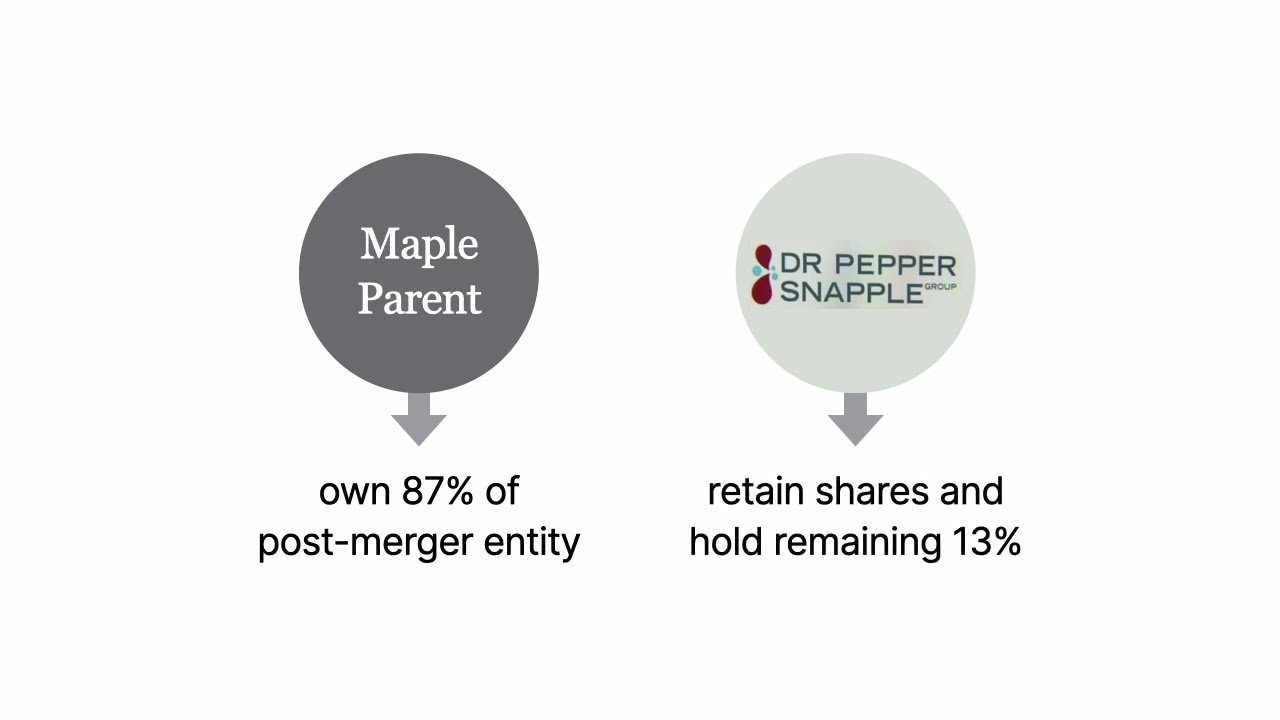
Uploaded March 2025 | Updated September 2026, 3 weeks ago
Get more case briefs explained with Quimbee. Quimbee has over 42,700 case briefs (and counting) keyed to 988 casebooks ► quimbee.com/case-briefs-overview
City of North Miami Beach General Employees’ Retirement Plan v. Dr Pepper Snapple Group, Inc.
Delaware Court of Chancery
189 A.3d 188 (2018)
Under Delaware law, when a corporation undergoes a merger or consolidation, dissenting stockholders may have the right to force the company to buy back their shares for fair market value as determined through a judicial appraisal process.
This appraisal remedy is only available to shareholders of a constituent corporation, a term we define in City of North Miami Beach general employees retirement plan versus Doctor Pepper Snapple Group.
Doctor Pepper Snapple Group and Keurig Green Mountain, two beverage companies, plan to merge through a reverse triangular merger.
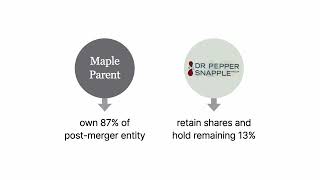
To effectuate the transaction, Doctor Pepper planned to form a wholly owned subsidiary, Salt Merger Sub, which would merge with and into Maple Parent Holdings Corporation, Keurig's indirect owner. Upon completion of the transaction, Keurig would be an indirect wholly owned subsidiary of Doctor Pepper. Maple parents equity holders would own eighty seven percent of the post merger entity, and Doctor Pepper's stockholders would retain their shares and hold the remaining thirteen percent.
Want more details on this case? Get the rule of law, issues, holding and reasonings, and more case facts here: quimbee.com/cases/city-of-north-miami-beach-general-employees-retirement-plan-v-dr-pepper-snapple-group-inc
The Quimbee App features over 42,700 case briefs keyed to 988 casebooks. Try it free for 7 days! ► quimbee.com/case-briefs-overview
Have Questions about this Case? Submit your questions and get answers from a real attorney here: quimbee.com/cases/city-of-north-miami-beach-general-employees-retirement-plan-v-dr-pepper-snapple-group-inc
Did we just become best friends? Stay connected to Quimbee here:
Subscribe to our YouTube Channel ► youtube.com/subscription_center?add_user=QuimbeeDotCom
Quimbee Case Brief App ► quimbee.com/case-briefs-overview
Facebook ► facebook.com/quimbeedotcom
Twitter ► twitter.com/quimbeedotcom
#casebriefs #lawcases #casesummaries
Get more case briefs explained with Quimbee. Quimbee has over 42,700 case briefs (and counting) keyed to 988 casebooks ► quimbee.com/case-briefs-overview
City of North Miami Beach General Employees’ Retirement Plan v. Dr Pepper Snapple Group, Inc.
Delaware Court of Chancery
189 A.3d 188 (2018)
Under Delaware law, when a corporation undergoes a merger or consolidation, dissenting stockholders may have the right to force the company to buy back their shares for fair market value as determined through a judicial appraisal process.
This appraisal remedy is only available to shareholders of a constituent corporation, a term we define in City of North Miami Beach general employees retirement plan versus Doctor Pepper Snapple Group.
Doctor Pepper Snapple Group and Keurig Green Mountain, two beverage companies, plan to merge through a reverse triangular merger.
To effectuate the transaction, Doctor Pepper planned to form a wholly owned subsidiary, Salt Merger Sub, which would merge with and into Maple Parent Holdings Corporation, Keurig's indirect owner. Upon completion of the transaction, Keurig would be an indirect wholly owned subsidiary of Doctor Pepper. Maple parents equity holders would own eighty seven percent of the post merger entity, and Doctor Pepper's stockholders would retain their shares and hold the remaining thirteen percent.
Want more details on this case? Get the rule of law, issues, holding and reasonings, and more case facts here: quimbee.com/cases/city-of-north-miami-beach-general-employees-retirement-plan-v-dr-pepper-snapple-group-inc
The Quimbee App features over 42,700 case briefs keyed to 988 casebooks. Try it free for 7 days! ► quimbee.com/case-briefs-overview
Have Questions about this Case? Submit your questions and get answers from a real attorney here: quimbee.com/cases/city-of-north-miami-beach-general-employees-retirement-plan-v-dr-pepper-snapple-group-inc
Did we just become best friends? Stay connected to Quimbee here:
Subscribe to our YouTube Channel ► youtube.com/subscription_center?add_user=QuimbeeDotCom
Quimbee Case Brief App ► quimbee.com/case-briefs-overview
Facebook ► facebook.com/quimbeedotcom
Twitter ► twitter.com/quimbeedotcom
#casebriefs #lawcases #casesummaries