Uploaded October 2026 | Updated November 2026, 3 days ago
Chapter helps you compare every Medicare Advantage, Medicare Supplement, and Part D plan for free, with support before and after enrollment. Call 510-961-3329 or visit chapter.com/erin
Feeling unsure about your financial future? My team at Root Financial can help: learn.rootfinancial.com/erin
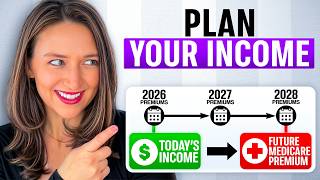
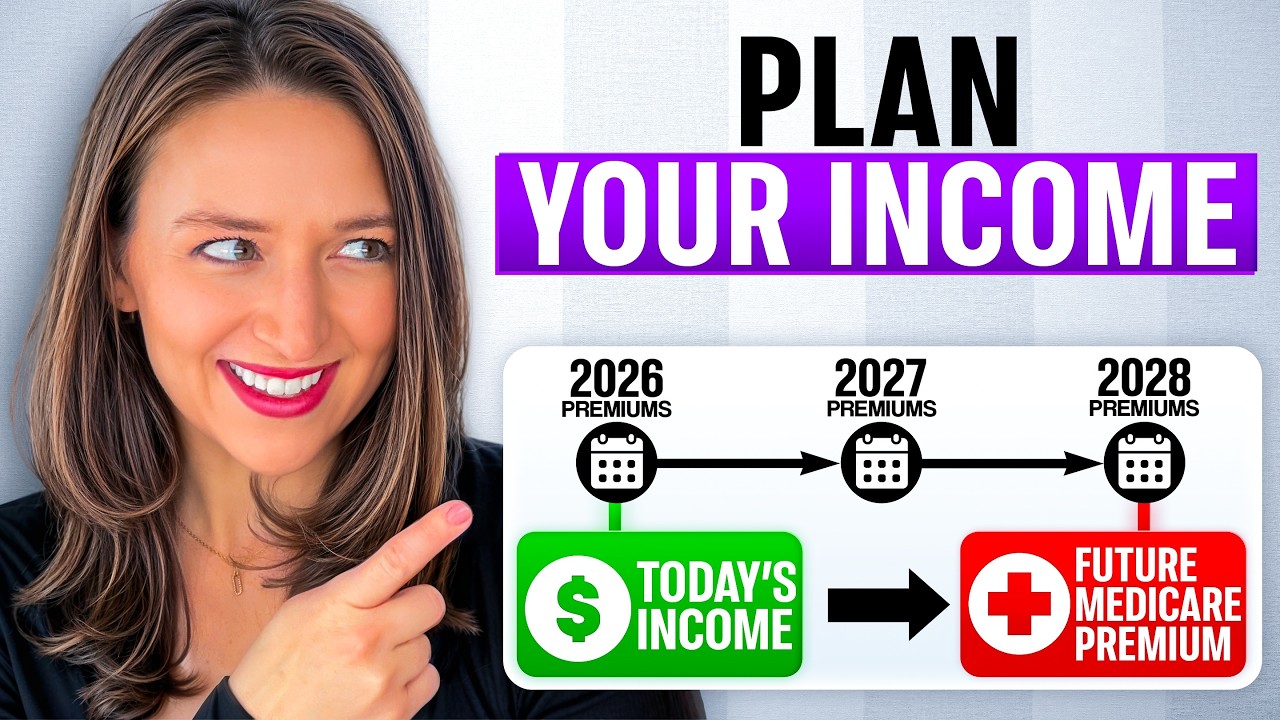
How do you plan for IRMAA when Medicare looks back two years, and being just $1 over the limit can cost you thousands in extra Medicare premiums?
In this video, I break down exactly how IRMAA, or Income-Related Monthly Adjustment Amount, works, including the 2026 and projected 2027 IRMAA brackets, how the two-year IRMAA lookback period affects your Medicare premiums, and why strategic retirement tax planning matters more than most retirees realize.
We’ll cover how IRMAA surcharges for Medicare Part B and Part D are calculated, how MAGI, or Modified Adjusted Gross Income, determines whether you pay higher Medicare premiums, and why even a small Roth conversion mistake can trigger costly surcharges.
I’ll also walk through how financial planners use IRMAA guardrails, income buffers, and Roth conversion strategies before RMD age to reduce lifetime taxes and avoid unnecessary Medicare costs.
If you are approaching retirement, already on Medicare, planning Roth conversions, managing required minimum distributions, or trying to reduce future Medicare IRMAA surcharges, this video will help you understand the smartest ways to plan ahead.
Topics covered:
• IRMAA brackets for 2026 and projected 2027
• Medicare Part B and Part D surcharges explained
• How the two-year IRMAA lookback works
• Roth conversion strategies to minimize IRMAA
• How IRMAA affects high-income retirees
• Retirement tax planning and Medicare planning
• How to avoid costly IRMAA mistakes
• IRMAA planning before Social Security and RMDs
Whether you are worried about Medicare premium increases, tax-efficient retirement withdrawals, or how to optimize retirement income, understanding IRMAA could save you thousands.
00:00 - Intro
01:19 - What IRMAA Actually Is
03:09 - Why You Cannot Predict IRMAA With Perfect Precision
03:19 - The First Layer: The Two-Year Lookback
03:56 - The Second Layer: The Thresholds Move Every Year
05:11 - Why a Dollar Over the Line Is So Painful
07:51 - How Professionals Actually Plan Around the Uncertainty
10:16 - The Three Planning Styles
10:22 - The First Style: The Aggressive Optimizer
10:45 - The Second Style: The Moderate Planner
11:22 - The Third Style: Intentional IRMAA Acceptance
13:16 - A Step-by-Step Framework You Can Use
13:23 - Step 1: Know Your MAGI Formula
13:53 - Step 2: Forecast Your Baseline Income
14:06 - Step 3: Estimate the Future Bracket
14:31 - Step 4: Leave Margin
14:46 - The Hidden Opportunity Inside the Two-Year Lookback
17:21 - Bloopers
Chapter and its affiliates are not connected with or endorsed by any government entity or the federal Medicare program. Chapter Advisory, LLC represents Medicare Advantage HMO, PPO, and PFFS organizations and stand alone prescription drug plans that have a Medicare contract. Enrollment depends on the plan’s contract renewal. While we have a database of every Medicare plan nationwide and can help you to search among all plans, we have contracts with many but not all plans. As a result, we do not offer every plan available in your area. Currently we represent 50 organizations which offer 18,160 products nationwide. We search and recommend all plans, even those we don’t directly offer. You can contact a licensed Chapter agent to find out the number of products available in your specific area. Please contact Medicare.gov, 1-800-Medicare, or your local State Health Insurance Program (SHIP) to get information on all of your options.
Erin Moriarity has a financial relationship with Chapter and may receive
compensation if you use this affiliate link. Chapter is not affiliated with Root Financial Partners, LLC.
Advisory services are offered through Root Financial Partners, LLC, an SEC-registered investment adviser. This content is intended for informational and educational purposes only and should not be considered personalized investment, tax, or legal advice. Viewing this content does not create an advisory relationship with Root Financial. We do not provide tax preparation or legal services. Always consult an investment, tax or legal professional regarding your specific situation. The strategies, case studies, and examples discussed may not be suitable for everyone. They are hypothetical and for illustrative and educational purposes only. They do not reflect actual client results and are not guarantees of future performance. All investments involve risk, including the potential loss of principal.
Comments reflect the views of individual users and do not necessarily represent the views of Root Financial. They are not verified, may not be accurate and should not be considered testimonials or endorsements.
Chapter helps you compare every Medicare Advantage, Medicare Supplement, and Part D plan for free, with support before and after enrollment. Call 510-961-3329 or visit chapter.com/erin
Feeling unsure about your financial future? My team at Root Financial can help: learn.rootfinancial.com/erin
How do you plan for IRMAA when Medicare looks back two years, and being just $1 over the limit can cost you thousands in extra Medicare premiums?
In this video, I break down exactly how IRMAA, or Income-Related Monthly Adjustment Amount, works, including the 2026 and projected 2027 IRMAA brackets, how the two-year IRMAA lookback period affects your Medicare premiums, and why strategic retirement tax planning matters more than most retirees realize.
We’ll cover how IRMAA surcharges for Medicare Part B and Part D are calculated, how MAGI, or Modified Adjusted Gross Income, determines whether you pay higher Medicare premiums, and why even a small Roth conversion mistake can trigger costly surcharges.
I’ll also walk through how financial planners use IRMAA guardrails, income buffers, and Roth conversion strategies before RMD age to reduce lifetime taxes and avoid unnecessary Medicare costs.
If you are approaching retirement, already on Medicare, planning Roth conversions, managing required minimum distributions, or trying to reduce future Medicare IRMAA surcharges, this video will help you understand the smartest ways to plan ahead.
Topics covered:
• IRMAA brackets for 2026 and projected 2027
• Medicare Part B and Part D surcharges explained
• How the two-year IRMAA lookback works
• Roth conversion strategies to minimize IRMAA
• How IRMAA affects high-income retirees
• Retirement tax planning and Medicare planning
• How to avoid costly IRMAA mistakes
• IRMAA planning before Social Security and RMDs
Whether you are worried about Medicare premium increases, tax-efficient retirement withdrawals, or how to optimize retirement income, understanding IRMAA could save you thousands.
00:00 - Intro
01:19 - What IRMAA Actually Is
03:09 - Why You Cannot Predict IRMAA With Perfect Precision
03:19 - The First Layer: The Two-Year Lookback
03:56 - The Second Layer: The Thresholds Move Every Year
05:11 - Why a Dollar Over the Line Is So Painful
07:51 - How Professionals Actually Plan Around the Uncertainty
10:16 - The Three Planning Styles
10:22 - The First Style: The Aggressive Optimizer
10:45 - The Second Style: The Moderate Planner
11:22 - The Third Style: Intentional IRMAA Acceptance
13:16 - A Step-by-Step Framework You Can Use
13:23 - Step 1: Know Your MAGI Formula
13:53 - Step 2: Forecast Your Baseline Income
14:06 - Step 3: Estimate the Future Bracket
14:31 - Step 4: Leave Margin
14:46 - The Hidden Opportunity Inside the Two-Year Lookback
17:21 - Bloopers
Chapter and its affiliates are not connected with or endorsed by any government entity or the federal Medicare program. Chapter Advisory, LLC represents Medicare Advantage HMO, PPO, and PFFS organizations and stand alone prescription drug plans that have a Medicare contract. Enrollment depends on the plan’s contract renewal. While we have a database of every Medicare plan nationwide and can help you to search among all plans, we have contracts with many but not all plans. As a result, we do not offer every plan available in your area. Currently we represent 50 organizations which offer 18,160 products nationwide. We search and recommend all plans, even those we don’t directly offer. You can contact a licensed Chapter agent to find out the number of products available in your specific area. Please contact Medicare.gov, 1-800-Medicare, or your local State Health Insurance Program (SHIP) to get information on all of your options.
Erin Moriarity has a financial relationship with Chapter and may receive
compensation if you use this affiliate link. Chapter is not affiliated with Root Financial Partners, LLC.
Advisory services are offered through Root Financial Partners, LLC, an SEC-registered investment adviser. This content is intended for informational and educational purposes only and should not be considered personalized investment, tax, or legal advice. Viewing this content does not create an advisory relationship with Root Financial. We do not provide tax preparation or legal services. Always consult an investment, tax or legal professional regarding your specific situation. The strategies, case studies, and examples discussed may not be suitable for everyone. They are hypothetical and for illustrative and educational purposes only. They do not reflect actual client results and are not guarantees of future performance. All investments involve risk, including the potential loss of principal.
Comments reflect the views of individual users and do not necessarily represent the views of Root Financial. They are not verified, may not be accurate and should not be considered testimonials or endorsements.