Uploaded August 2026 | Updated September 2026, 1 week ago
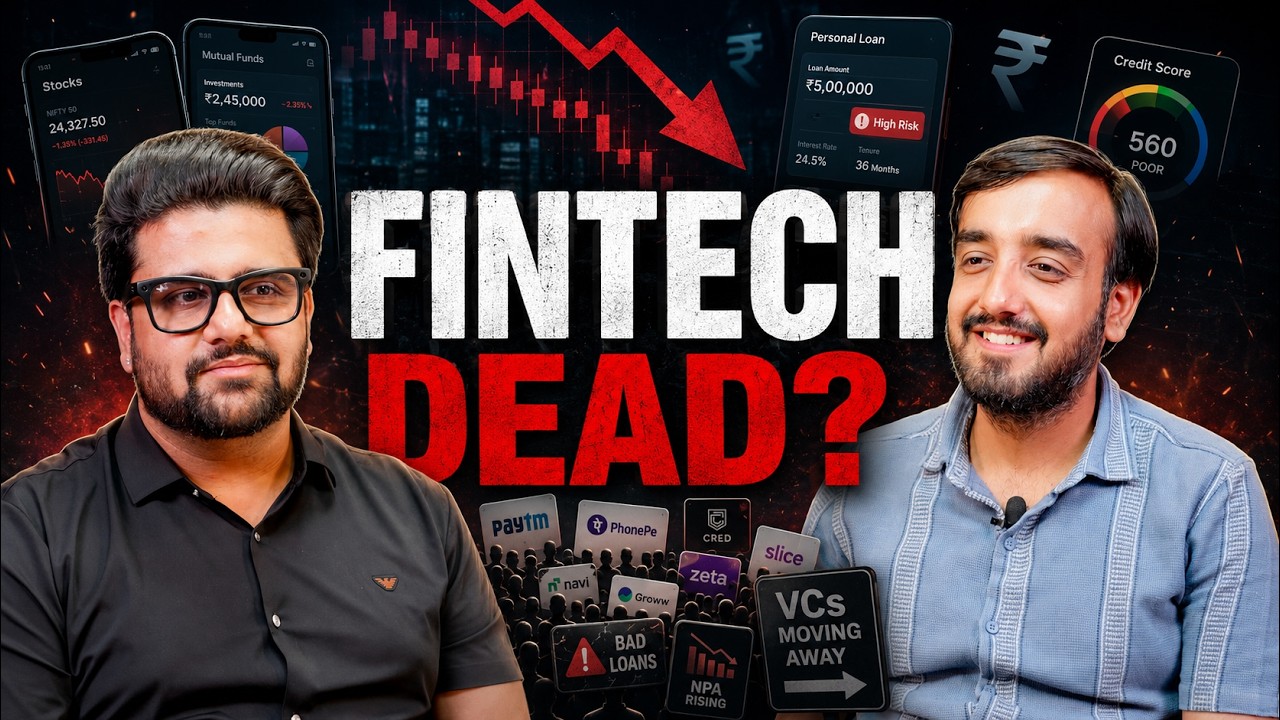
Is the Indian fintech boom slowing down, or is the industry simply running out of new ideas?
In this video, we discuss why venture capital investors are becoming more cautious about fintech startups in India. From stock broking platforms and mutual fund apps to personal lending and digital credit, almost every fintech company appears to be offering the same products.
While lending can generate strong margins, rising bad loans, poor credit assessment, high customer acquisition costs and weak differentiation can quickly destroy profitability. If a company earns a 5% margin but loses 10% of its loan book, the maths is brutal—the business is losing money, not building wealth.
We also discuss:
Why so many startups are entering stock broking
Why lending looks profitable on paper
How fintech companies earn through interest margins
The growing problem of bad loans and NPAs
Why VCs are moving away from repetitive fintech models
Whether Indian fintech still has room for innovation
What the next successful fintech startup must solve
India still has a massive credit and investment opportunity. But copying Zerodha, Groww, Slice or other successful fintech companies is not a business strategy. The next big fintech company will need a real competitive advantage, better underwriting, stronger distribution and a profitable business model.
Watch the complete discussion and share your opinion: Is Indian fintech dead, overcrowded, or waiting for its next big idea?
Subscribe for more conversations on startups, venture capital, business models, funding and entrepreneurship in India.
#Fintech #IndianStartups #VentureCapital #FintechIndia #StartupFunding #PersonalLoans #StockBroking #BadLoans #Entrepreneurship #BusinessPodcast
Buy Our Course: lapaas.com/solopreneur.html
Or Contact 9540065704 (On working hours, else WhatsApp)
For exclusive update about Sahil khanna and lapaas, the content we don't share anywhere else- Join our whatsapp channel for- whatsapp.com/channel/0029Va4ra9d3LdQQCLgqsk3g
👉🏻Download Our App
✔️Android- play.google.com/store/apps/details?id=com.rpy.lapaasfktfcs
✔️iOS - apps.apple.com/in/app/lapaas-business-booster/id6499594612
Understand your personality and how it affects your career and relationships. Take our free personality test- lapaas.com/personality-test.html
Our Top Rated Playlist
FREE Advanced Digital Marketing Course- youtube.com/watch?v=zdi5hEDNmzY&list=PLd9tDukllEepYrfX-zy6NLbLRmHdPsukE
Sales Training- youtube.com/watch?v=aM61r0NzHlM&list=PLd9tDukllEepN-4WYflD_PMJFFLfgyrTR
FREE Online MBA- youtube.com/watch?v=5aQcV0AwTwg&list=PLd9tDukllEeqz6gPFwa-YrE1_YFzOac_W
Case Study/ Business Model- youtube.com/watch?v=d213u36SR70&list=PLd9tDukllEerp-eIuJVlVwZCEmd6fAo2q
#AskSahilKhanna
Follow Intellectual Indies-
Website- lapaas.com
Instagram- https://www.instagram.com/intellectua...
Twitter- twitter.com/intellectualins
Facebook Page- https://www.facebook.com/Intellectual...
YouTube Channel-youtube.com/channel/UC_s0g4QdprLkyyN2MDpef7Q
Is the Indian fintech boom slowing down, or is the industry simply running out of new ideas?
In this video, we discuss why venture capital investors are becoming more cautious about fintech startups in India. From stock broking platforms and mutual fund apps to personal lending and digital credit, almost every fintech company appears to be offering the same products.
While lending can generate strong margins, rising bad loans, poor credit assessment, high customer acquisition costs and weak differentiation can quickly destroy profitability. If a company earns a 5% margin but loses 10% of its loan book, the maths is brutal—the business is losing money, not building wealth.
We also discuss:
Why so many startups are entering stock broking
Why lending looks profitable on paper
How fintech companies earn through interest margins
The growing problem of bad loans and NPAs
Why VCs are moving away from repetitive fintech models
Whether Indian fintech still has room for innovation
What the next successful fintech startup must solve
India still has a massive credit and investment opportunity. But copying Zerodha, Groww, Slice or other successful fintech companies is not a business strategy. The next big fintech company will need a real competitive advantage, better underwriting, stronger distribution and a profitable business model.
Watch the complete discussion and share your opinion: Is Indian fintech dead, overcrowded, or waiting for its next big idea?
Subscribe for more conversations on startups, venture capital, business models, funding and entrepreneurship in India.
#Fintech #IndianStartups #VentureCapital #FintechIndia #StartupFunding #PersonalLoans #StockBroking #BadLoans #Entrepreneurship #BusinessPodcast
Buy Our Course: lapaas.com/solopreneur.html
Or Contact 9540065704 (On working hours, else WhatsApp)
For exclusive update about Sahil khanna and lapaas, the content we don't share anywhere else- Join our whatsapp channel for- whatsapp.com/channel/0029Va4ra9d3LdQQCLgqsk3g
👉🏻Download Our App
✔️Android- play.google.com/store/apps/details?id=com.rpy.lapaasfktfcs
✔️iOS - apps.apple.com/in/app/lapaas-business-booster/id6499594612
Understand your personality and how it affects your career and relationships. Take our free personality test- lapaas.com/personality-test.html
Our Top Rated Playlist
FREE Advanced Digital Marketing Course- youtube.com/watch?v=zdi5hEDNmzY&list=PLd9tDukllEepYrfX-zy6NLbLRmHdPsukE
Sales Training- youtube.com/watch?v=aM61r0NzHlM&list=PLd9tDukllEepN-4WYflD_PMJFFLfgyrTR
FREE Online MBA- youtube.com/watch?v=5aQcV0AwTwg&list=PLd9tDukllEeqz6gPFwa-YrE1_YFzOac_W
Case Study/ Business Model- youtube.com/watch?v=d213u36SR70&list=PLd9tDukllEerp-eIuJVlVwZCEmd6fAo2q
#AskSahilKhanna
Follow Intellectual Indies-
Website- lapaas.com
Instagram- https://www.instagram.com/intellectua...
Twitter- twitter.com/intellectualins
Facebook Page- https://www.facebook.com/Intellectual...
YouTube Channel-youtube.com/channel/UC_s0g4QdprLkyyN2MDpef7Q