Uploaded April 2025 | Updated September 2026, 2 weeks ago
Get more case briefs explained with Quimbee. Quimbee has over 42,700 case briefs (and counting) keyed to 988 casebooks ► quimbee.com/case-briefs-overview
Suburban Realty Co. v. United States
United States Court of Appeals for the Fifth Circuit
615 F.2d 171 (1980)
A business's profits from the sale of capital assets are classified as capital gains and taxed at the lower capital gains rate. But profits from sales in the ordinary course of operations are taxed as ordinary income.
In Suburban Realty Company versus United States, a taxpayer argued that profits from its real estate sales, should be considered capital gains.
Suburban Realty Company owned an interest in approximately seventeen hundred acres of land in Texas.
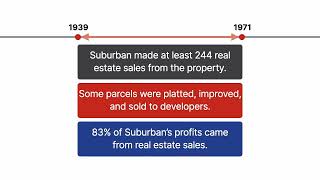
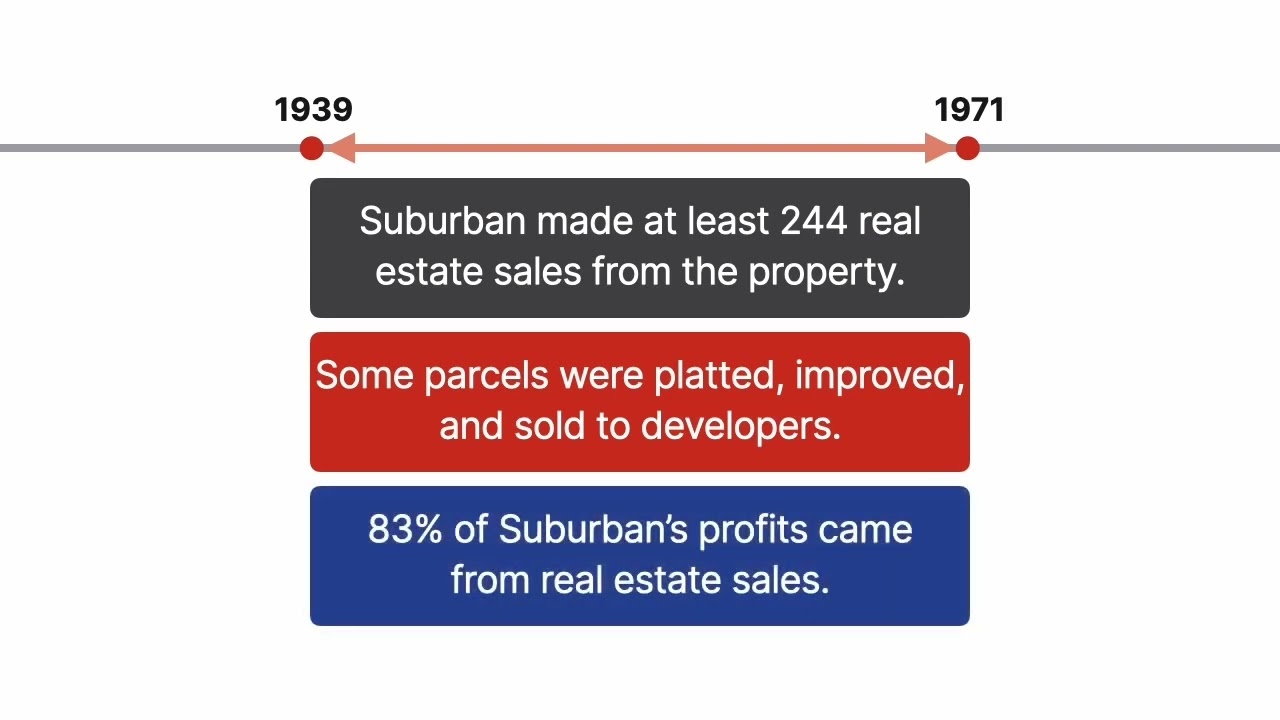
Between nineteen thirty nine and nineteen seventy one, Suburban made at least two hundred forty four real estate sales from the property. Some parcels were platted, improved, and sold to developers.
During this time, eighty three percent of Suburban's profits came from real estate sales.
In nineteen fifty seven, the state proposed building a highway across the property, causing land values to skyrocket.
Starting in nineteen sixty six, Suburban began investing in stocks and bonds, and also received substantial income from these investments.
Between nineteen sixty eight and nineteen seventy one, Suburban sold six unimproved tracts from the property.
Initially, Suburban reported the income from these sales as ordinary income. Later, Suburban filed a claim for a refund, asserting that the proceeds were entitled to capital gains treatment. The Internal Revenue Service denied Suburban's claim.
Suburban sued the government for a refund.
After a non jury trial, the district court dismissed Suburban's complaint. Suburban appealed to the fifth circuit.
Want more details on this case? Get the rule of law, issues, holding and reasonings, and more case facts here: quimbee.com/cases/suburban-realty-co-v-united-states
The Quimbee App features over 42,700 case briefs keyed to 988 casebooks. Try it free for 7 days! ► quimbee.com/case-briefs-overview
Have Questions about this Case? Submit your questions and get answers from a real attorney here: quimbee.com/cases/suburban-realty-co-v-united-states
Did we just become best friends? Stay connected to Quimbee here:
Subscribe to our YouTube Channel ► youtube.com/subscription_center?add_user=QuimbeeDotCom
Quimbee Case Brief App ► quimbee.com/case-briefs-overview
Facebook ► facebook.com/quimbeedotcom
Twitter ► twitter.com/quimbeedotcom
#casebriefs #lawcases #casesummaries
Get more case briefs explained with Quimbee. Quimbee has over 42,700 case briefs (and counting) keyed to 988 casebooks ► quimbee.com/case-briefs-overview
Suburban Realty Co. v. United States
United States Court of Appeals for the Fifth Circuit
615 F.2d 171 (1980)
A business's profits from the sale of capital assets are classified as capital gains and taxed at the lower capital gains rate. But profits from sales in the ordinary course of operations are taxed as ordinary income.
In Suburban Realty Company versus United States, a taxpayer argued that profits from its real estate sales, should be considered capital gains.
Suburban Realty Company owned an interest in approximately seventeen hundred acres of land in Texas.
Between nineteen thirty nine and nineteen seventy one, Suburban made at least two hundred forty four real estate sales from the property. Some parcels were platted, improved, and sold to developers.
During this time, eighty three percent of Suburban's profits came from real estate sales.
In nineteen fifty seven, the state proposed building a highway across the property, causing land values to skyrocket.
Starting in nineteen sixty six, Suburban began investing in stocks and bonds, and also received substantial income from these investments.
Between nineteen sixty eight and nineteen seventy one, Suburban sold six unimproved tracts from the property.
Initially, Suburban reported the income from these sales as ordinary income. Later, Suburban filed a claim for a refund, asserting that the proceeds were entitled to capital gains treatment. The Internal Revenue Service denied Suburban's claim.
Suburban sued the government for a refund.
After a non jury trial, the district court dismissed Suburban's complaint. Suburban appealed to the fifth circuit.
Want more details on this case? Get the rule of law, issues, holding and reasonings, and more case facts here: quimbee.com/cases/suburban-realty-co-v-united-states
The Quimbee App features over 42,700 case briefs keyed to 988 casebooks. Try it free for 7 days! ► quimbee.com/case-briefs-overview
Have Questions about this Case? Submit your questions and get answers from a real attorney here: quimbee.com/cases/suburban-realty-co-v-united-states
Did we just become best friends? Stay connected to Quimbee here:
Subscribe to our YouTube Channel ► youtube.com/subscription_center?add_user=QuimbeeDotCom
Quimbee Case Brief App ► quimbee.com/case-briefs-overview
Facebook ► facebook.com/quimbeedotcom
Twitter ► twitter.com/quimbeedotcom
#casebriefs #lawcases #casesummaries