Uploaded September 2026 | Updated November 2026, 4 days ago
Real assets vs. paper assets isn't simply a question of which investment produces the highest return. Robert Kiyosaki argues that investors should also ask what they actually own, how much control they have, what risks they accept, and who benefits from the financial product they're buying.
In this episode of The Rich Dad Radio Show, Robert Kiyosaki challenges conventional thinking about 401(k)s, mutual funds, bonds, and annuities—and explains why he prefers owning real assets that can produce cash flow or serve as stores of value.
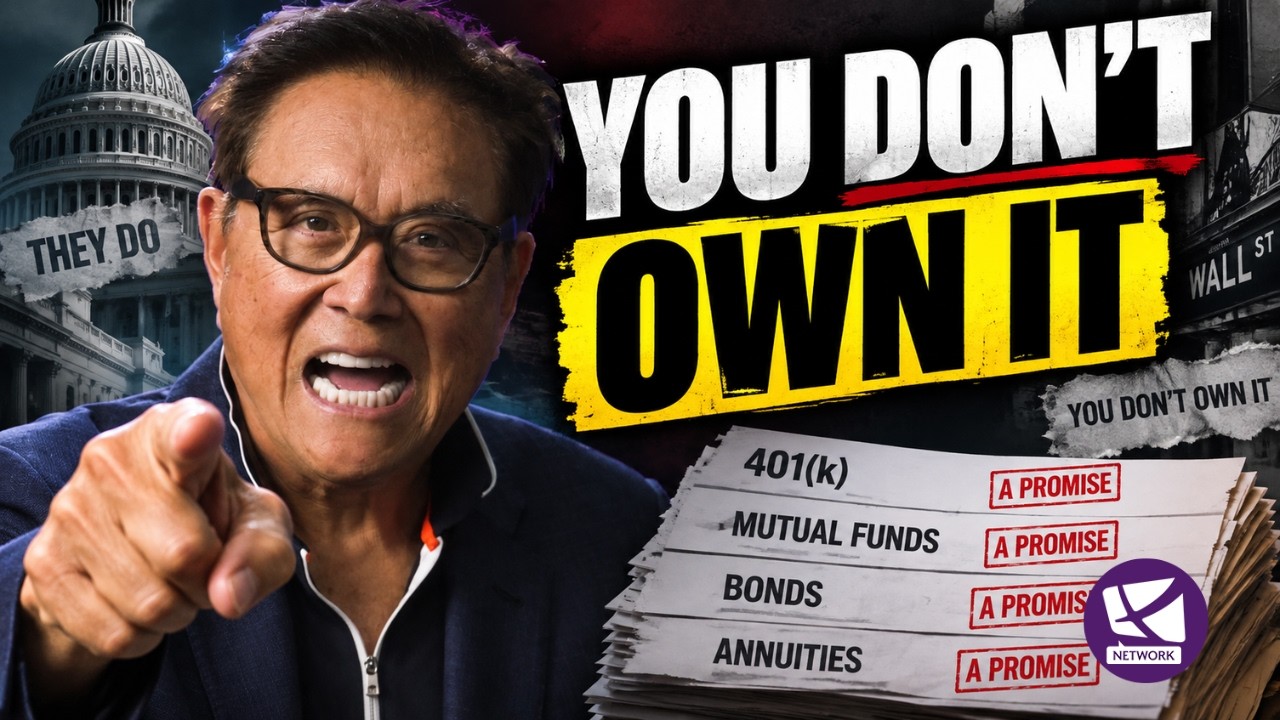
Robert starts with a fundamental distinction: an asset and a promise aren't necessarily the same thing.
When you invest through a retirement account, mutual fund, bond, or annuity, you may own a financial claim or contract whose value depends on markets, institutions, managers, issuers, and the rules governing that investment.
Robert contrasts that with assets he considers more tangible or controllable. A rental property can produce rent. A business can generate income. Gold and silver don't depend on a company promising to repay you. For Robert, that distinction between ownership and dependency is central to understanding risk.
In this episode, you'll learn:
-The difference between real assets and paper assets
-Why Robert questions conventional retirement strategies
-What investors should understand about 401(k)s, mutual funds, bonds, and annuities
-Why owning several funds doesn't automatically create true diversification
-How systemic market risk can affect multiple investments at once
-Why investment fees matter more over long periods
-How mutual fund capital gains distributions can create unexpected tax consequences
-The Rich Dad definition of good debt vs. bad debt
-Why Robert prefers cash-flowing assets
-How financial education can help investors evaluate Wall Street products
-Why control and ownership matter when evaluating an investment
-What questions investors should ask before trusting their financial future to any product or institution
The central lesson isn't that every paper asset is automatically bad or every real asset is automatically good.
It's that investors need to understand what they own.
Robert argues that financial education gives investors the ability to distinguish between an asset and a liability, understand how an investment produces income, identify who controls it, evaluate the risks, and decide whether that investment actually moves them closer to financial freedom.
00:00 Tax Bill on Phantom Gains
00:53 Meet the Four Horsemen
01:38 Promises vs Real Assets
04:25 Annuities and the Tax Trap
05:49 Market Shock Gold Ad Break
07:02 Rigged System and Escape Plan
08:17 Diversification Myth Exposed
11:36 Fees and Compounding Damage
13:11 Private Deals Promo Break
15:47 Mutual Fund Tax Time Bomb
17:09 Good Debt and Real Ownership
19:20 Who Built the Trap
20:55 Financial Education and Freedom
22:39 Final Takeaways and Sign Off
-----
Disclaimer: The information provided in this video is for educational and informational purposes only. It should not be considered as financial advice or a recommendation to buy or sell any financial instrument or engage in any financial activity.
The content presented here is based on the speaker's personal opinions and research, which may not always be accurate or up-to-date. Financial markets and investments carry inherent risks, and individuals should conduct their own research and seek professional advice before making any financial decisions.
Real assets vs. paper assets isn't simply a question of which investment produces the highest return. Robert Kiyosaki argues that investors should also ask what they actually own, how much control they have, what risks they accept, and who benefits from the financial product they're buying.
In this episode of The Rich Dad Radio Show, Robert Kiyosaki challenges conventional thinking about 401(k)s, mutual funds, bonds, and annuities—and explains why he prefers owning real assets that can produce cash flow or serve as stores of value.
Robert starts with a fundamental distinction: an asset and a promise aren't necessarily the same thing.
When you invest through a retirement account, mutual fund, bond, or annuity, you may own a financial claim or contract whose value depends on markets, institutions, managers, issuers, and the rules governing that investment.
Robert contrasts that with assets he considers more tangible or controllable. A rental property can produce rent. A business can generate income. Gold and silver don't depend on a company promising to repay you. For Robert, that distinction between ownership and dependency is central to understanding risk.
In this episode, you'll learn:
-The difference between real assets and paper assets
-Why Robert questions conventional retirement strategies
-What investors should understand about 401(k)s, mutual funds, bonds, and annuities
-Why owning several funds doesn't automatically create true diversification
-How systemic market risk can affect multiple investments at once
-Why investment fees matter more over long periods
-How mutual fund capital gains distributions can create unexpected tax consequences
-The Rich Dad definition of good debt vs. bad debt
-Why Robert prefers cash-flowing assets
-How financial education can help investors evaluate Wall Street products
-Why control and ownership matter when evaluating an investment
-What questions investors should ask before trusting their financial future to any product or institution
The central lesson isn't that every paper asset is automatically bad or every real asset is automatically good.
It's that investors need to understand what they own.
Robert argues that financial education gives investors the ability to distinguish between an asset and a liability, understand how an investment produces income, identify who controls it, evaluate the risks, and decide whether that investment actually moves them closer to financial freedom.
00:00 Tax Bill on Phantom Gains
00:53 Meet the Four Horsemen
01:38 Promises vs Real Assets
04:25 Annuities and the Tax Trap
05:49 Market Shock Gold Ad Break
07:02 Rigged System and Escape Plan
08:17 Diversification Myth Exposed
11:36 Fees and Compounding Damage
13:11 Private Deals Promo Break
15:47 Mutual Fund Tax Time Bomb
17:09 Good Debt and Real Ownership
19:20 Who Built the Trap
20:55 Financial Education and Freedom
22:39 Final Takeaways and Sign Off
-----
Disclaimer: The information provided in this video is for educational and informational purposes only. It should not be considered as financial advice or a recommendation to buy or sell any financial instrument or engage in any financial activity.
The content presented here is based on the speaker's personal opinions and research, which may not always be accurate or up-to-date. Financial markets and investments carry inherent risks, and individuals should conduct their own research and seek professional advice before making any financial decisions.