Uploaded September 2026 | Updated November 2026, 3 days ago
Chapter helps you compare every Medicare Advantage, Medicare Supplement, and Part D plan for free, with support before and after enrollment. Call 510-961-3329 or visit chapter.com/erin
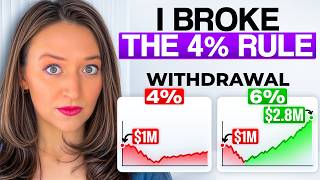
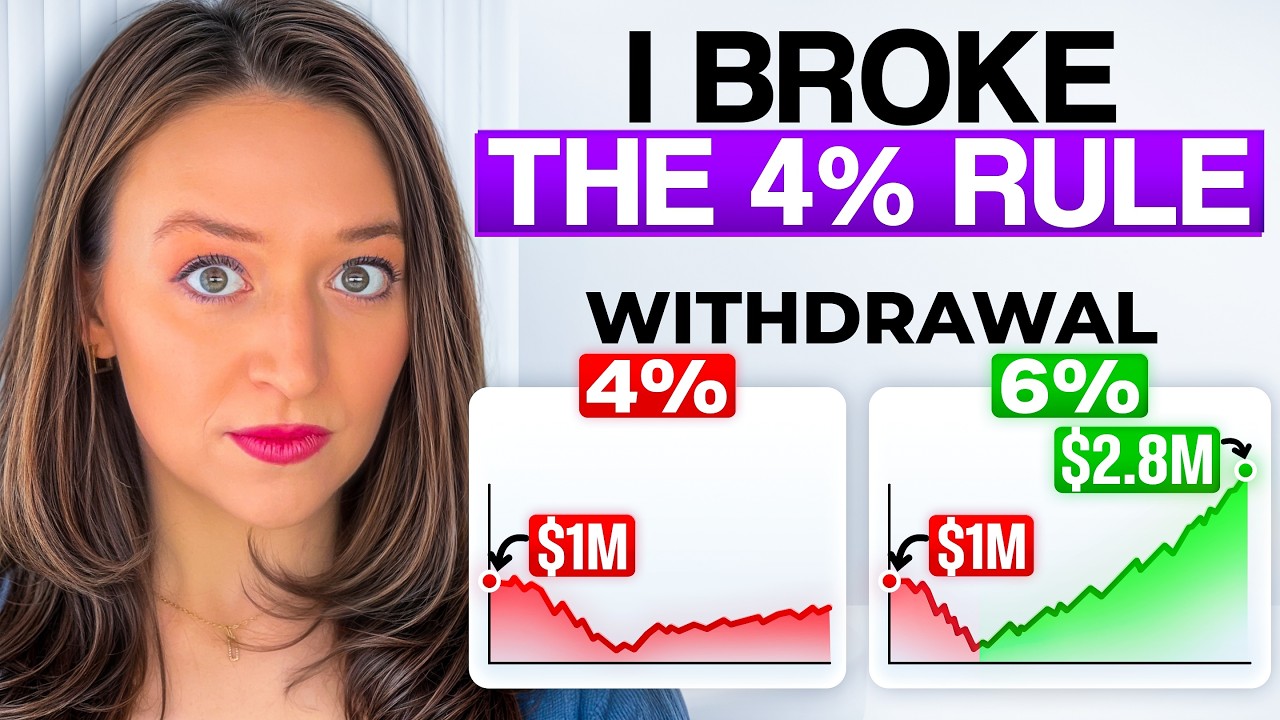
Can you safely withdraw 6% from a $1 million retirement portfolio instead of following the traditional 4% rule?
In this video, I test a higher retirement withdrawal rate against one of the most difficult retirement periods in modern U.S. history: the market declines, stagflation, and high inflation that followed an October 1968 retirement.
Using historical market returns and inflation data, I model a $1 million portfolio beginning with a $60,000 withdrawal.
The retiree then reduces real spending before freezing the portfolio withdrawal at $65,380. Despite starting with a 6% withdrawal rate, the portfolio finishes the 30-year period with approximately $2.8 million in nominal value.
But portfolio survival is only part of retirement income planning.
Inflation steadily reduces the purchasing power of a frozen withdrawal, so we calculate the retiree’s income in inflation-adjusted dollars.
We then add Social Security benefits and annual cost-of-living adjustments to see how inflation-protected retirement income changes the outcome for single retirees and married couples.
This analysis does not prove that a 6% withdrawal rate is always safe.
It shows how flexible retirement spending, Social Security income, sequence-of-returns risk, and declining expenses later in retirement can affect how much you may safely withdraw from a $1 million portfolio, and whether you can spend more during the healthiest years of retirement without running out of money.
00:00 - Intro
01:17 - The Retirement Spending Curve Nobody Talks About
04:27 - Where the 4% Rule Actually Comes From
05:25 - A Different Way to Structure the Withdrawal
07:00 - What the Portfolio Actually Does
08:17 - The Catch Nobody Mentions
09:56 - Bringing Social Security Back Into the Picture
13:29 - What Two Social Security Checks Change
15:14 - Comparing This to the Real World
16:33 - The Caveats You Need to Hear
19:00 - Bloopers
Chapter and its affiliates are not connected with or endorsed by any government entity or the federal Medicare program. Chapter Advisory, LLC represents Medicare Advantage HMO, PPO, and PFFS organizations and stand alone prescription drug plans that have a Medicare contract. Enrollment depends on the plan’s contract renewal. While we have a database of every Medicare plan nationwide and can help you to search among all plans, we have contracts with many but not all plans. As a result, we do not offer every plan available in your area. Currently we represent 50 organizations which offer 18,160 products nationwide. We search and recommend all plans, even those we don’t directly offer. You can contact a licensed Chapter agent to find out the number of products available in your specific area. Please contact Medicare.gov, 1-800-Medicare, or your local State Health Insurance Program (SHIP) to get information on all of your options.
Erin Moriarity has a financial relationship with Chapter and may receive
compensation if you use this affiliate link. Chapter is not affiliated with Root Financial Partners, LLC.
Feeling unsure about your financial future? My team at Root Financial can help: learn.rootfinancial.com/erin
Connect with me on LinkedIn for charts & daily retirement insights: linkedin.com/in/erintalksmoney
Some of my favorite books: amzn.to/3KF3tlr
Camera & equipment I use: amzn.to/3Z20lof
Join the family & subscribe to my channel here: youtube.com/c/ErinTalksMoney
Thanks for watching, I appreciate you!
Advisory services are offered through Root Financial Partners, LLC, an SEC-registered investment adviser. This content is intended for informational and educational purposes only and should not be considered personalized investment, tax, or legal advice. Viewing this content does not create an advisory relationship with Root Financial. We do not provide tax preparation or legal services. Always consult an investment, tax or legal professional regarding your specific situation. The strategies, case studies, and examples discussed may not be suitable for everyone. They are hypothetical and for illustrative and educational purposes only. They do not reflect actual client results and are not guarantees of future performance. All investments involve risk, including the potential loss of principal.
Comments reflect the views of individual users and do not necessarily represent the views of Root Financial. They are not verified, may not be accurate and should not be considered testimonials or endorsements.
Chapter helps you compare every Medicare Advantage, Medicare Supplement, and Part D plan for free, with support before and after enrollment. Call 510-961-3329 or visit chapter.com/erin
Can you safely withdraw 6% from a $1 million retirement portfolio instead of following the traditional 4% rule?
In this video, I test a higher retirement withdrawal rate against one of the most difficult retirement periods in modern U.S. history: the market declines, stagflation, and high inflation that followed an October 1968 retirement.
Using historical market returns and inflation data, I model a $1 million portfolio beginning with a $60,000 withdrawal.
The retiree then reduces real spending before freezing the portfolio withdrawal at $65,380. Despite starting with a 6% withdrawal rate, the portfolio finishes the 30-year period with approximately $2.8 million in nominal value.
But portfolio survival is only part of retirement income planning.
Inflation steadily reduces the purchasing power of a frozen withdrawal, so we calculate the retiree’s income in inflation-adjusted dollars.
We then add Social Security benefits and annual cost-of-living adjustments to see how inflation-protected retirement income changes the outcome for single retirees and married couples.
This analysis does not prove that a 6% withdrawal rate is always safe.
It shows how flexible retirement spending, Social Security income, sequence-of-returns risk, and declining expenses later in retirement can affect how much you may safely withdraw from a $1 million portfolio, and whether you can spend more during the healthiest years of retirement without running out of money.
00:00 - Intro
01:17 - The Retirement Spending Curve Nobody Talks About
04:27 - Where the 4% Rule Actually Comes From
05:25 - A Different Way to Structure the Withdrawal
07:00 - What the Portfolio Actually Does
08:17 - The Catch Nobody Mentions
09:56 - Bringing Social Security Back Into the Picture
13:29 - What Two Social Security Checks Change
15:14 - Comparing This to the Real World
16:33 - The Caveats You Need to Hear
19:00 - Bloopers
Chapter and its affiliates are not connected with or endorsed by any government entity or the federal Medicare program. Chapter Advisory, LLC represents Medicare Advantage HMO, PPO, and PFFS organizations and stand alone prescription drug plans that have a Medicare contract. Enrollment depends on the plan’s contract renewal. While we have a database of every Medicare plan nationwide and can help you to search among all plans, we have contracts with many but not all plans. As a result, we do not offer every plan available in your area. Currently we represent 50 organizations which offer 18,160 products nationwide. We search and recommend all plans, even those we don’t directly offer. You can contact a licensed Chapter agent to find out the number of products available in your specific area. Please contact Medicare.gov, 1-800-Medicare, or your local State Health Insurance Program (SHIP) to get information on all of your options.
Erin Moriarity has a financial relationship with Chapter and may receive
compensation if you use this affiliate link. Chapter is not affiliated with Root Financial Partners, LLC.
Feeling unsure about your financial future? My team at Root Financial can help: learn.rootfinancial.com/erin
Connect with me on LinkedIn for charts & daily retirement insights: linkedin.com/in/erintalksmoney
Some of my favorite books: amzn.to/3KF3tlr
Camera & equipment I use: amzn.to/3Z20lof
Join the family & subscribe to my channel here: youtube.com/c/ErinTalksMoney
Thanks for watching, I appreciate you!
Advisory services are offered through Root Financial Partners, LLC, an SEC-registered investment adviser. This content is intended for informational and educational purposes only and should not be considered personalized investment, tax, or legal advice. Viewing this content does not create an advisory relationship with Root Financial. We do not provide tax preparation or legal services. Always consult an investment, tax or legal professional regarding your specific situation. The strategies, case studies, and examples discussed may not be suitable for everyone. They are hypothetical and for illustrative and educational purposes only. They do not reflect actual client results and are not guarantees of future performance. All investments involve risk, including the potential loss of principal.
Comments reflect the views of individual users and do not necessarily represent the views of Root Financial. They are not verified, may not be accurate and should not be considered testimonials or endorsements.