Uploaded October 2026 | Updated November 2026, 1 hour ago
Feeling unsure about your financial future? My team at Root Financial can help: learn.rootfinancial.com/erin
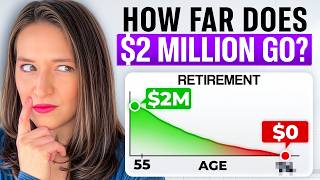
How long will $2 million last in retirement? Could you retire early with $2 million—or could you still run out of money?
In this video, we follow three retirement scenarios that begin with the same $2 million. A single retiree stops working at 55, lives in a high-cost-of-living area, and draws heavily from her portfolio. A married couple retires at 67 with Social Security covering a substantial share of their expenses. A third retiree uses part of her savings to purchase an immediate annuity and create a more predictable income stream.
We break down each household’s essential and discretionary expenses, Social Security income, annual portfolio withdrawals, and inflation-adjusted balances. You’ll see how spending cuts can extend a portfolio’s life, what happens to a couple’s plan when one spouse dies, and why a fixed annuity payment loses purchasing power over time.
If you’re wondering whether $2 million is enough to retire, the answer depends on when you retire, how much you spend, what other income you receive, and how willing you are to adjust. These are simplified illustrations with assumed returns, not predictions of anyone’s retirement.
00:00 - Intro
01:00 - Let’s Talk About the Examples
02:11 - Example One: She Retires Early and Keeps an Expensive Lifestyle
05:25 - Her Flexible Spending Rule
07:37 - Example Two: A Couple Retires at a Traditional Age
12:00 - Example Three: A Retiree Creates Predictable Income
16:55 - What These Examples Do and Don’t Tell Us
20:43 - Bloopers
Connect with me on LinkedIn for charts & daily retirement insights: linkedin.com/in/erintalksmoney
Some of my favorite books: amzn.to/3KF3tlr
Camera & equipment I use: amzn.to/3Z20lof
Join the family & subscribe to my channel here: youtube.com/c/ErinTalksMoney
Thanks for watching, I appreciate you!
Advisory services are offered through Root Financial Partners, LLC, an SEC-registered investment adviser. This content is intended for informational and educational purposes only and should not be considered personalized investment, tax, or legal advice. Viewing this content does not create an advisory relationship with Root Financial. We do not provide tax preparation or legal services. Always consult an investment, tax or legal professional regarding your specific situation. The strategies, case studies, and examples discussed may not be suitable for everyone. They are hypothetical and for illustrative and educational purposes only. They do not reflect actual client results and are not guarantees of future performance. All investments involve risk, including the potential loss of principal.
Comments reflect the views of individual users and do not necessarily represent the views of Root Financial. They are not verified, may not be accurate and should not be considered testimonials or endorsements.
Feeling unsure about your financial future? My team at Root Financial can help: learn.rootfinancial.com/erin
How long will $2 million last in retirement? Could you retire early with $2 million—or could you still run out of money?
In this video, we follow three retirement scenarios that begin with the same $2 million. A single retiree stops working at 55, lives in a high-cost-of-living area, and draws heavily from her portfolio. A married couple retires at 67 with Social Security covering a substantial share of their expenses. A third retiree uses part of her savings to purchase an immediate annuity and create a more predictable income stream.
We break down each household’s essential and discretionary expenses, Social Security income, annual portfolio withdrawals, and inflation-adjusted balances. You’ll see how spending cuts can extend a portfolio’s life, what happens to a couple’s plan when one spouse dies, and why a fixed annuity payment loses purchasing power over time.
If you’re wondering whether $2 million is enough to retire, the answer depends on when you retire, how much you spend, what other income you receive, and how willing you are to adjust. These are simplified illustrations with assumed returns, not predictions of anyone’s retirement.
00:00 - Intro
01:00 - Let’s Talk About the Examples
02:11 - Example One: She Retires Early and Keeps an Expensive Lifestyle
05:25 - Her Flexible Spending Rule
07:37 - Example Two: A Couple Retires at a Traditional Age
12:00 - Example Three: A Retiree Creates Predictable Income
16:55 - What These Examples Do and Don’t Tell Us
20:43 - Bloopers
Connect with me on LinkedIn for charts & daily retirement insights: linkedin.com/in/erintalksmoney
Some of my favorite books: amzn.to/3KF3tlr
Camera & equipment I use: amzn.to/3Z20lof
Join the family & subscribe to my channel here: youtube.com/c/ErinTalksMoney
Thanks for watching, I appreciate you!
Advisory services are offered through Root Financial Partners, LLC, an SEC-registered investment adviser. This content is intended for informational and educational purposes only and should not be considered personalized investment, tax, or legal advice. Viewing this content does not create an advisory relationship with Root Financial. We do not provide tax preparation or legal services. Always consult an investment, tax or legal professional regarding your specific situation. The strategies, case studies, and examples discussed may not be suitable for everyone. They are hypothetical and for illustrative and educational purposes only. They do not reflect actual client results and are not guarantees of future performance. All investments involve risk, including the potential loss of principal.
Comments reflect the views of individual users and do not necessarily represent the views of Root Financial. They are not verified, may not be accurate and should not be considered testimonials or endorsements.