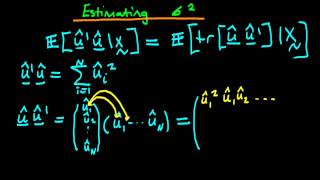Uploaded November 2013 | Updated September 2026, 2 hours ago
In this video the explicit form of an unbiased estimator of the error variance is derived.
This video explains the concept of the Orthogonal Projection Operator in Ordinary Least Squares estimation, and derives its explicit matrix form.
Check out oxbridge-tutor.co.uk/graduate-econometrics-course for course materials, and information regarding updates on each of the courses. Check out ben-lambert.com/econometrics-course-problem-sets-and-data for course materials, and information regarding updates on each of the courses. Quite excitingly (for me at least), I am about to publish a whole series of new videos on Bayesian statistics on youtube. See here for information: ben-lambert.com/bayesian Accompanying this series, there will be a book: amazon.co.uk/gp/product/1473916364/ref=pe_3140701_247401851_em_1p_0_ti
In this video the explicit form of an unbiased estimator of the error variance is derived.
This video explains the concept of the Orthogonal Projection Operator in Ordinary Least Squares estimation, and derives its explicit matrix form.
Check out oxbridge-tutor.co.uk/graduate-econometrics-course for course materials, and information regarding updates on each of the courses. Check out ben-lambert.com/econometrics-course-problem-sets-and-data for course materials, and information regarding updates on each of the courses. Quite excitingly (for me at least), I am about to publish a whole series of new videos on Bayesian statistics on youtube. See here for information: ben-lambert.com/bayesian Accompanying this series, there will be a book: amazon.co.uk/gp/product/1473916364/ref=pe_3140701_247401851_em_1p_0_ti