Uploaded April 2025 | Updated November 2026, 5 hours ago
I once joked that saving a dollar a day at 1.7% daily interest would turn into $30,000 in a year. Which, for the record, is terrible financial advice. You’re not finding 1.7% daily interest anywhere legitimate. That’s lottery ticket math.
So let’s do some real financial thinking.
Here’s a basic rule: don’t take out a loan to call a taxi for your burrito.
If someone is offering to lend you money for that, they’re not helping you—they’re exploiting you.
---
Check out the main channel! @polymathematic
---
There are basically two good reasons to borrow money:
You’re offering up collateral.
That’s when the lender can recover something of value if you don’t pay them back—your house, your car, something they can repossess. That’s why mortgages and car loans exist. There's something tangible backing the agreement.
You’re using the loan to generate income.
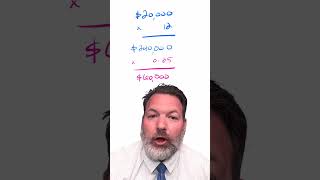
Maybe you’ve got a business idea that could bring in real revenue. Say you believe you can make $20,000 a month. Over a year, that’s $240,000 in revenue. Even with a 25% profit margin, you’re taking home $60,000. Pretty good.
But maybe you need $20,000 upfront to make it happen. So you go to a bank, explain your plan, and ask for a loan. If they agree your idea is viable, they’ll lend you the $20,000—maybe at 10% interest. That means you pay back $22,000, but in return, you net $60,000. That’s a deal that makes sense.
Calling a taxi for your burrito? Not so much.
There’s no collateral—they can’t repo the burrito. And there’s no return on investment. You're not launching a taco empire. You’re just... full.
And look, I get it. No one likes working on an empty stomach. But if you're borrowing money just to satisfy a passing craving, that’s not financial planning—it’s just digging a deeper hole.
I’m not a hardcore “no debt ever” kind of guy. But if you don’t have the money to call the taxi and buy the burrito, you don’t have the money for it.
Don’t take on debt for something that disappears by lunchtime.
#SmartMoneyMoves #FinancialLiteracy #MoneyMistakes
Watch more Math Videos:
Math Minis: youtube.com/playlist?list=PLrc8spN1b3jkQynJ5heNvSs72gCPj_hwj
Math Minutes: youtube.com/playlist?list=PLrc8spN1b3jmVFYwHiuMzCYJ0y_yiwUge
Number Sense: youtube.com/playlist?list=PLrc8spN1b3jksKkY_oarNFEFAHjrIV97U
MATHCOUNTS: youtube.com/playlist?list=PLrc8spN1b3jlqDkZXtby9lnEaOBy7-ZY0
Follow Tim Ricchuiti:
TikTok: tiktok.com/@polymathematic
Mathstodon: https://mathstodon.xyz/@polymathematic
Instagram: instagram.com/polymathematicnet
Reddit: reddit.com/user/polymath-matic
Facebook: facebook.com/polymathematic
I once joked that saving a dollar a day at 1.7% daily interest would turn into $30,000 in a year. Which, for the record, is terrible financial advice. You’re not finding 1.7% daily interest anywhere legitimate. That’s lottery ticket math.
So let’s do some real financial thinking.
Here’s a basic rule: don’t take out a loan to call a taxi for your burrito.
If someone is offering to lend you money for that, they’re not helping you—they’re exploiting you.
---
Check out the main channel! @polymathematic
---
There are basically two good reasons to borrow money:
You’re offering up collateral.
That’s when the lender can recover something of value if you don’t pay them back—your house, your car, something they can repossess. That’s why mortgages and car loans exist. There's something tangible backing the agreement.
You’re using the loan to generate income.
Maybe you’ve got a business idea that could bring in real revenue. Say you believe you can make $20,000 a month. Over a year, that’s $240,000 in revenue. Even with a 25% profit margin, you’re taking home $60,000. Pretty good.
But maybe you need $20,000 upfront to make it happen. So you go to a bank, explain your plan, and ask for a loan. If they agree your idea is viable, they’ll lend you the $20,000—maybe at 10% interest. That means you pay back $22,000, but in return, you net $60,000. That’s a deal that makes sense.
Calling a taxi for your burrito? Not so much.
There’s no collateral—they can’t repo the burrito. And there’s no return on investment. You're not launching a taco empire. You’re just... full.
And look, I get it. No one likes working on an empty stomach. But if you're borrowing money just to satisfy a passing craving, that’s not financial planning—it’s just digging a deeper hole.
I’m not a hardcore “no debt ever” kind of guy. But if you don’t have the money to call the taxi and buy the burrito, you don’t have the money for it.
Don’t take on debt for something that disappears by lunchtime.
#SmartMoneyMoves #FinancialLiteracy #MoneyMistakes
Watch more Math Videos:
Math Minis: youtube.com/playlist?list=PLrc8spN1b3jkQynJ5heNvSs72gCPj_hwj
Math Minutes: youtube.com/playlist?list=PLrc8spN1b3jmVFYwHiuMzCYJ0y_yiwUge
Number Sense: youtube.com/playlist?list=PLrc8spN1b3jksKkY_oarNFEFAHjrIV97U
MATHCOUNTS: youtube.com/playlist?list=PLrc8spN1b3jlqDkZXtby9lnEaOBy7-ZY0
Follow Tim Ricchuiti:
TikTok: tiktok.com/@polymathematic
Mathstodon: https://mathstodon.xyz/@polymathematic
Instagram: instagram.com/polymathematicnet
Reddit: reddit.com/user/polymath-matic
Facebook: facebook.com/polymathematic