Uploaded January 2025 | Updated September 2026, 1 week ago
In this session, I report on another banner year for US equities, with the S&P 500 delivering a return of 24.88% for the year. I put this return in historical context (the 27th best year out of the last 97 years), as well as the two-year return of 57.42%, from 2023 and 2024 (the tenth best two-year return in the last century). After looking at the premiums you would have earned on stocks, relative to treasuries in 2024 and over history, I then turn to how the index is priced at the start of 2025. The PE ratio (using trailing, normalized or CAPE) is higher than historical norms, and the earning yield (EP) exceeded the ten year treasury rate at the start of 2025. While those are red flags, I present a fuller measure of a forward-looking ERP for the market, and argue for some nuance in how you read the numbers.
Slides: https://pages.stern.nyu.edu/~adamodar/pdfiles/blog/DataUpdate2for2025.pdf
Blog post: aswathdamodaran.blogspot.com/2025/01/data-update-2-for-2025-party-continued.html
Spreadsheets:
1. Historical returns on stocks: https://pages.stern.nyu.edu/~adamodar/pc/datasets/histretSP.xlsx
2. Implied ERP at the start of 2025: https://pages.stern.nyu.edu/~adamodar/pc/implprem/ERPJan25.xlsx
3. Historical implied ERP: https://pages.stern.nyu.edu/~adamodar/pc/datasets/histimpl.xls
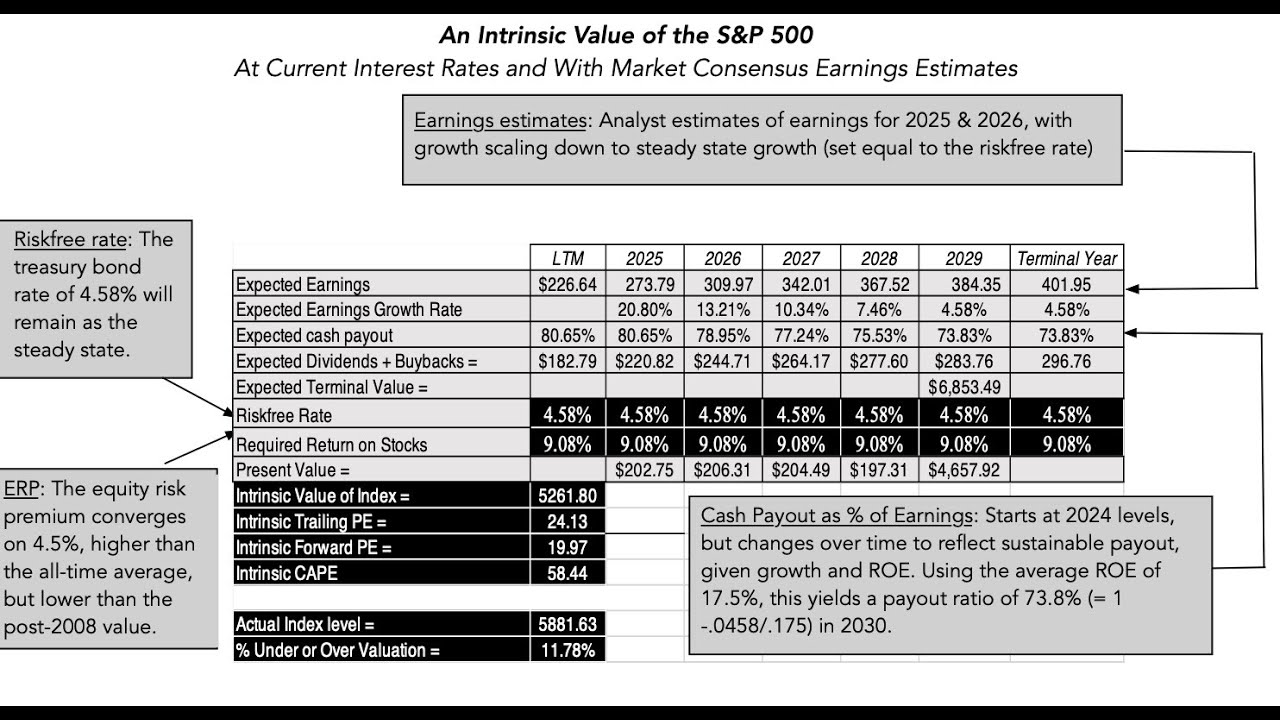
Valuation of the index
Spreadsheet: https://pages.stern.nyu.edu/~adamodar/pc/blog/S&PValueJan2025.xlsx
In this session, I report on another banner year for US equities, with the S&P 500 delivering a return of 24.88% for the year. I put this return in historical context (the 27th best year out of the last 97 years), as well as the two-year return of 57.42%, from 2023 and 2024 (the tenth best two-year return in the last century). After looking at the premiums you would have earned on stocks, relative to treasuries in 2024 and over history, I then turn to how the index is priced at the start of 2025. The PE ratio (using trailing, normalized or CAPE) is higher than historical norms, and the earning yield (EP) exceeded the ten year treasury rate at the start of 2025. While those are red flags, I present a fuller measure of a forward-looking ERP for the market, and argue for some nuance in how you read the numbers.
Slides: https://pages.stern.nyu.edu/~adamodar/pdfiles/blog/DataUpdate2for2025.pdf
Blog post: aswathdamodaran.blogspot.com/2025/01/data-update-2-for-2025-party-continued.html
Spreadsheets:
1. Historical returns on stocks: https://pages.stern.nyu.edu/~adamodar/pc/datasets/histretSP.xlsx
2. Implied ERP at the start of 2025: https://pages.stern.nyu.edu/~adamodar/pc/implprem/ERPJan25.xlsx
3. Historical implied ERP: https://pages.stern.nyu.edu/~adamodar/pc/datasets/histimpl.xls
Valuation of the index
Spreadsheet: https://pages.stern.nyu.edu/~adamodar/pc/blog/S&PValueJan2025.xlsx


